UPI Fraud: How to Get Your Money Back
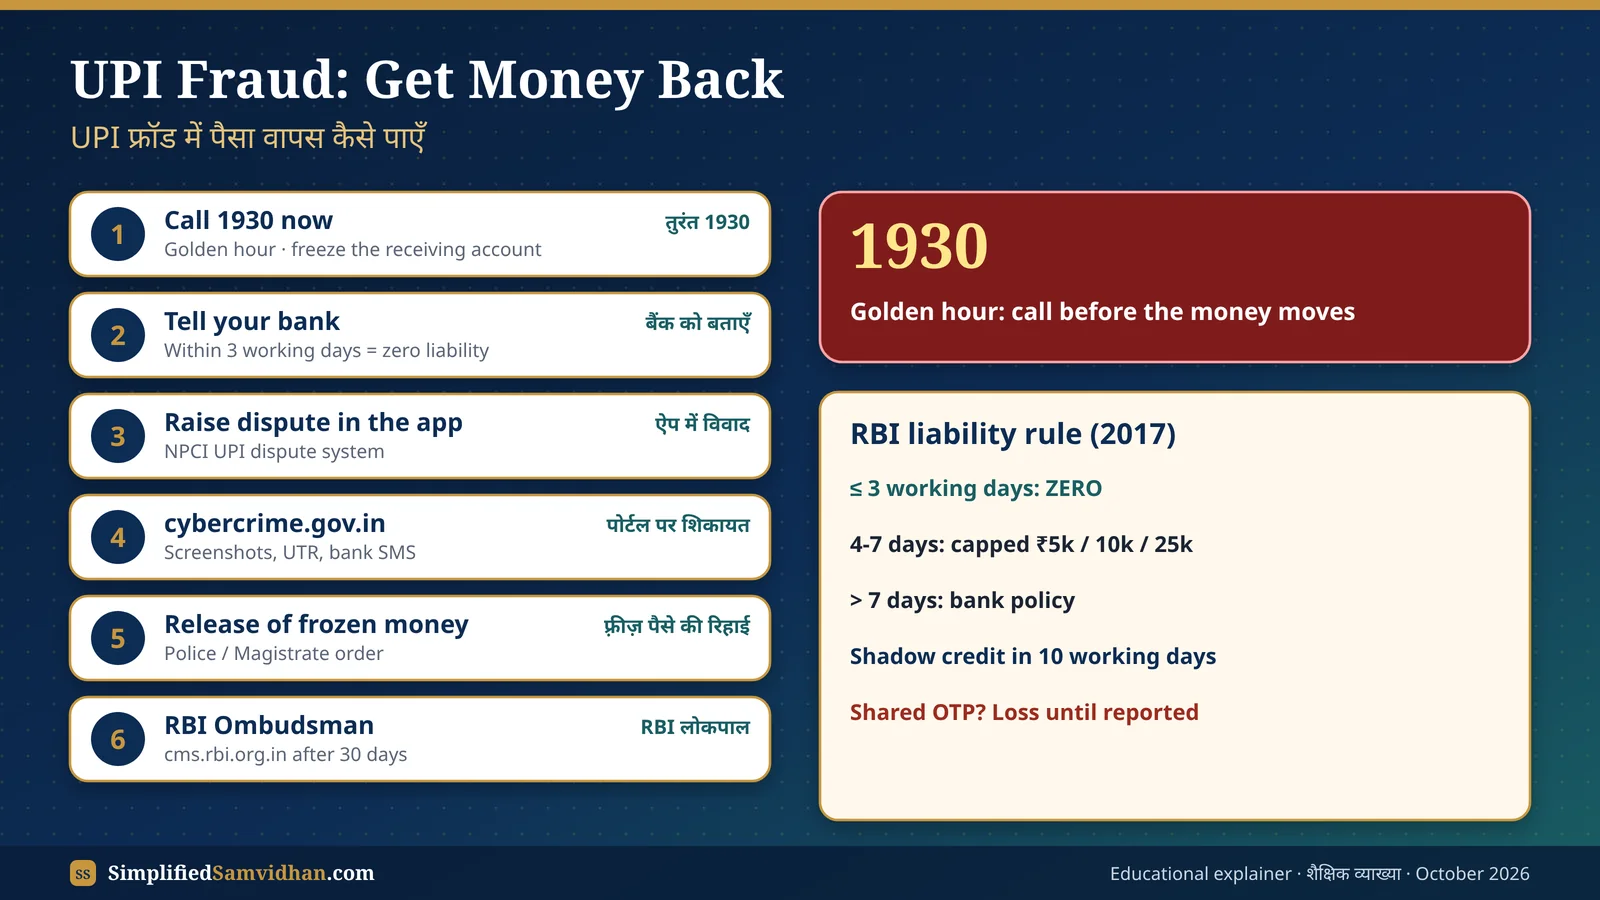
Two clocks start when money leaves your account: the golden hour for 1930 and the 3-working-day window for your bank. Here is what to do on each.
Know your caseUPI Fraud: Which Kind Is Yours?
| What happened | Type | How money comes back |
|---|---|---|
| Money left your account without your PIN or approval (SIM swap, hacked app, cloned card) | Unauthorised transaction | RBI 2017 rules: report to the bank within 3 working days for zero liability; shadow credit in 10 working days |
| You were tricked into sending money or entering your PIN to 'receive' money | Fraud you authorised | Not covered by zero liability. Call 1930 at once so the receiving account is frozen; money is released later on police or court order |
| Debited but the payment failed or the merchant did not get it | Failed transaction | Auto-reversal by T+1 day; if late, the bank pays ₹100 a day (RBI TAT circular, 20 Sep 2019) |
| Sent to the wrong UPI ID or number by mistake | Wrong transfer | Raise a dispute in the app and with your bank; the receiver's bank contacts the receiver. No automatic right, so act fast |
Step by stepHow to Get UPI Fraud Money Back: 6 Steps
- 1
☎️ Call 1930 within the golden hour
Give the UTR / transaction ID, amount, time and the fraudster's UPI ID. The system alerts the receiving bank to hold the money before it moves on.
- 2
🏦 Report to your bank within 3 working days
Call the bank's 24x7 fraud number or use its app or website to report the fraud and block UPI. Get a complaint number with date and time; the RBI rules require the bank to give you one. Reporting fast is what protects your money.
- 3
📱 Raise a dispute in the UPI app
In GPay, PhonePe, Paytm or BHIM open the transaction → 'Raise dispute' / 'Report a problem'. This enters NPCI's dispute system and gives you a second record.
- 4
💻 File on cybercrime.gov.in
Quote the 1930 number and upload screenshots and the bank SMS. See our step-by-step portal guide.
- 5
📜 Get frozen money released
If money was held in the fraudster's account, the cyber police or the Magistrate's court orders its return to you. Give your FIR, bank details and ID; follow up every week.
- 6
⚖️ Bank silent for 30 days? RBI Ombudsman
If the bank rejects your complaint or does not reply in 30 days, file free at cms.rbi.org.in under the RBI Integrated Ombudsman Scheme. The bank must settle an unauthorised-transaction complaint within 90 days.
RBI rulesRBI Zero Liability Rule: The 3-Day Window
RBI circular on customer protection, 6 July 2017 · Zero liability of a customer. A customer's entitlement to zero liability shall arise where the unauthorised transaction occurs in the following events: (i) Contributory fraud/ negligence/ deficiency on the part of the bank (irrespective of whether or not the transaction is reported by the customer). (ii) Third party breach where the deficiency lies neither with the bank nor with the customer but lies elsewhere in the system, and the customer notifies the bank within three working days of receiving the communication from the bank regarding the unauthorised transaction.
Reversal timeline. On being notified by the customer, the bank shall credit (shadow reversal) the amount involved in the unauthorised electronic transaction to the customer's account within 10 working days from the date of such notification by the customer …
| When you report to the bank | Your maximum loss (third-party breach) |
|---|---|
| Within 3 working days | Zero |
| 4 to 7 working days | Transaction value or the cap, whichever is lower: ₹5,000 (basic savings), ₹10,000 (savings accounts, credit cards up to ₹5 lakh limit), ₹25,000 (current accounts, credit cards above ₹5 lakh) |
| After 7 working days | As per the bank's board-approved policy |
| You shared your PIN or OTP | You bear the loss until you report it; the bank is liable after that |
Speed is everything. If someone else took your money, telling the bank within 3 working days means you lose nothing. If you were fooled into paying, the bank rules do not cover it, and only a fast 1930 call can freeze the money before the fraudster withdraws it.
🏠 Everyday analogy
Like a stolen bike: report it the same day and the police can stop it at the checkpost; report it after a week and it is already in pieces.
🇮🇳 Real Indian example
Suppose ₹12,000 is debited at night through a SIM-swap you never knew about. You report it to the bank the next morning. Under the 2017 rules the bank must put ₹12,000 back as a shadow credit within 10 working days while it investigates.
ConstitutionYour Money and the Constitution
Article 21: Life, liberty and privacy
Your savings and your financial data are part of a life with dignity and privacy; the RBI rules put the risk of system failure on the bank, not on you.
Article 14: Equal protection
Every bank must follow the same RBI customer-protection rules for every customer, whether in a metro or a village branch.
Practice MCQTest Yourself: Banking Fraud
Under the RBI's 2017 customer-protection rules, a customer has zero liability for an unauthorised electronic transaction caused by a third-party breach if the bank is informed within:
Doubts ClearedFrequently Asked Questions
Can I get money back after a UPI fraud?
Often, if you act fast. Unauthorised debits reported within 3 working days carry zero liability. If you paid the fraudster yourself, money comes back only if the 1930 complaint freezes it in time.
How long does a UPI fraud refund take?
For unauthorised transactions the bank must give a shadow credit within 10 working days and resolve within 90 days. Frozen money in a fraudster's account takes longer because it needs a police or court release.
What if the money was debited but the payment failed?
It should be reversed by the next day (T+1). If not, the bank must pay you ₹100 for each day of delay under the RBI's 2019 turnaround-time rules.
Where can I complain if my bank does not help?
After 30 days, or if the bank rejects your complaint, at cms.rbi.org.in under the RBI Integrated Ombudsman Scheme. It is free.
Sources and further readingSources We Checked
Facts checked on 23 October 2026 against the RBI circulars of 6 July 2017 and 20 September 2019, the RBI Integrated Ombudsman Scheme, 2021 and NPCI's UPI dispute process.
- RBI circular: Customer Protection, limiting liability of customers in unauthorised electronic banking transactions (6 July 2017)
- RBI circular: Harmonisation of turnaround time for failed transactions (20 September 2019)
- RBI Complaint Management System (Integrated Ombudsman)
- NPCI: UPI dispute redressal mechanism
- National Cyber Crime Reporting Portal (MHA, I4C)